If you’re a company owner, you must purchase commercial insurance. Many business owners appreciate the help of an experienced insurance agent when exploring their commercial insurance options. If your company is located near Wenatchee, WA, our team at Wenatchee Insurance Agency invites you to visit us and discuss your commercial insurance portfolio. We’ve been working with companies like yours since 2013.
Do You Need Key Person Insurance?
Your commercial insurance portfolio typically includes several types of coverage, such as property insurance, liability coverage, employee health insurance, and workers’ compensation. One additional type worth knowing about is key person insurance, sometimes called key man insurance. This is a life or disability policy purchased by a company for someone considered essential to its financial success, such as a founder, an influential leader, or a specialized expert.
With a key person policy, the company pays the premiums, and if that individual passes away or becomes incapacitated, the policy payout goes to the company. These policies are built on the idea that losing a key person could affect the company’s operations, client relationships, or overall financial stability. This coverage can provide valuable support if an important figure is no longer able to be involved with your company.
Contact Us Today for Your Appointment
Taking care of your business involves many aspects of management, including your choice of commercial insurance. Our team at Wenatchee Insurance Agency can help simplify the management of your commercial insurance portfolio. Companies in the Wenatchee, WA, area have learned that we provide great customer service. Give us a call for your appointment today.
As the population of Eastern Washington has continued to grow over the last few years, the availability of work for contractors has steadily grown as well. It has presented a major opportunity for the hustlers and workers who are great at their craft. Whether you have a gift for painting or are excellent at keeping bugs away, the opportunity to get jobs has grown with each new transplant to this state.
Jesse is an expert painter who owns a Moses Lake business and has worked on a lot of remodel projects as a subcontractor while the fixer upper economy has boomed. Despite the fact that Jesse has been working as a painter since he was 18, he had an accident occur at one of his jobs recently. While he was painting on the porch of a flip for a friend of his, he accidentally did substantial damage to the window frame where he was working.
The good news for Jesse is that he had secured General Liability Insurance via Wenatchee Insurance. Many of his fellow painters only carry commercial auto insurance for their trucks. But Jorge realized that even though it wasn’t necessary since his jobs didn’t explicitly require it, having a general liability policy was a way for him to protect both his reputation and his future business. This incident reinforced the potential financial and legal consequences of being uninsured. It highlighted the variety of risks contractors face while working and why having the right types of coverage is important. So what made Jesse decide to buy this additional coverage?
Definition & Importance of General Liability Coverage
General liability is essential liability coverage for Washington contractors. It provides a safety net against third-party claims of injury or property damage. These claims can come from either bodily injury or property damage to people, places, or things that are not part of your business. If your damage is extensive enough, a third-party lawsuit could bankrupt your future. Given that contractors in Washington require a license, insurance and registering with Labor and Industries, it is good to have a plan in place with agents you can work with. Having this relatively affordable coverage ensures that your businesses can operate without the constant fear of potentially crippling legal challenges and financial losses.
If you are working a job, whether it is big or small, you always run the risk of a potential lawsuit if you create accidental property damage. It not only helps in managing the expenses associated with repair but also secures the contractor’s financial stability and reputation in the long run making sure that defense costs are covered and any judgements are taken care of. Every contractor benefits from this coverage, particularly those involved in high-risk trades like electrical, plumbing, or construction.
We’ve established that General Liability Insurance will cover risks such as bodily injury, property damage, copyright infringement, reputational harm, and advertising injury. For contractor insurance coverage, the focus is placed directly on the property damage and bodily injury. Your general liability insurance coverage will address the common claims that contractors face. While it does provide coverage for claims of bodily injury of people who are not employed by your business in some capacity, it’s important to realize that it does not cover you or your employees. That requires workers compensation insurance rather than general liability.
Workers Compensation in Washington state is purchased through the state managed program at the Department of Labor & Industries. Labeling your employees as 1099 independent contractors is not enough and they must past a 7-part test.
For contractors, this insurance offers several benefits. While you are working on or bidding for construction projects it provides protection against lawsuits, enhances credibility, and offers peace of mind. With appropriate policy limits in place similar to what Jesse had for his painting business, it becomes easier to bid on jobs and work knowing that any liability claims that might arise will be covered by the insurance company rather than your bank account.
No Requirement, Big Risk: Why General Liability Insurance is a Must for Washington Contractors
General Liability Coverage Types
In Washington, contractors can choose from various types of business insurance coverage. These can include professional liability insurance to protect your work, inland marine insurance to protect tools, and commercial auto policies. Each of these coverage types are tailored to address specific risks associated with small business operations specifically targeted at the work that you do. It’s important for contractors to understand what each coverage entails to ensure they are adequately protected against potential risks and liabilities inherent in their specific field of work. The three main areas that General Liability addresses for contractors are listed below.
Protection Against Bodily Injury Claims
General liability insurance plays a critical role in protecting against bodily injury claims that are brought by people not associated with or affiliated with your construction business. This coverage is essential for contractors as it mitigates the financial impact of accidents that may occur on the job site causing a bystander to become injured. It benefits you by ensuring the contractor is not held personally liable for these incidents. It covers medical expenses and legal fees, which are vital in maintaining the business’s operations during such events.
Protection Against Property Damage Claims
This type of insurance covers potential liabilities that could arise from damage caused during construction activities. Given that damaging the location where you are working is the most likely potential claim, this physical damage coverage is the most important piece of this insurance policy. While it only protects you for accidental damage, mistakes can be expensive and hard to fund. For contractors, understanding how this coverage works is crucial as it protects against claims that could otherwise severely impact their financial stability.
Legal Defense Coverage
Legal Defense Coverage is a key component of general liability insurance for contractors. It offers significant benefits by covering legal expenses and providing relief during stressful legal claims. This coverage is essential in protecting contractors from the high costs and reputational damage that can result from legal disputes. Why would you want to pay these out of pocket when a small premium cost shifts the burden to the insurance company? Our friend Jesse understood this part.
Legal Requirements for Contractors in Washington
Contractors in Washington are required to carry a contractors insurance policy. To register as a Contractor in Washington state, you must have general liability of at least $200,000 in public liability and $50,000 in property or $250,000 in combined single limit. In addition, you need a surety bond of $30,000 for general contractors or $15,000 for specialty.
But remember, many job sites and general contractors demand proof of insurance before allowing your work to commence. Complying with these requirements not only fulfills legal obligations, but carrying a general liability insurance policy can also give contractors a competitive edge in the marketplace since you can immediately produce a certificate of insurance.
Wenatchee Insurance specializes in helping contractors like Jesse protect themselves and their futures with customized insurance plans. Working with an experienced commercial insurance agent ensures that contractors receive the necessary coverage that matches the scope of their work, providing an essential safeguard for their businesses. That customized commercial insurance plan is provided through Wenatchee Insurance Agency.
Let’s talk about the million-dollar question: how much does commercial auto insurance cost? Well, not a million dollars, thank goodness. But it can vary, like choosing between a fancy coffee from Little Red’s Espresso or a cup from your coffee maker at home.
The cost depends on several factors. First, there’s the number of vehicles. If you’ve got a fleet of FedEx delivery trucks, like the ones you see hustling from Leavenworth to Omak, you’re going to pay more than if you’re just insuring a single delivery van.
Then there’s the type of vehicle. A slick sports car used for pizza delivery is going to cost more to insure than a modest pickup truck for auto parts. Plus, if your employees are as careful as a herd of buffaloes in a China shop, your claims history might push those premiums up.
The driving records of your employees also play a big part. If your star driver has a clean record, you’re in great shape. But if Bob from accounting keeps getting tickets for speeding through the roundabout near Central Washington University, that’s going to hurt the bottom line.
And don’t forget coverage limits and deductibles. The higher the limit and the lower the deductible, the more you’re going to pay. It’s like deciding between getting an extra scoop of ice cream with sprinkles or sticking with the single – more coverage costs more.
So, on average, you might pay around $147 to $188 per month per vehicle. But just like with everything in life, we shop around and compare.
It’s like finding the best apple at the market – you’ve got to look around to get the best deal. As an independent insurance agency, we work with multiple companies to find our clients good rates in Washington state.
Just think of Wenatchee Insurance as your trusty sidekick, ready to jump in and save the day when things go awry.
Topics: Progressive, Commercial Auto, company car, collision coverage, collision coverage, delivery, Wenatchee Insurance, Chelan County, Grant County, Douglas County, Okanogan,
Leasing an office space is common for new businesses that may not be able to (or may not want to) invest in an entire office building. However, this does raise some questions when you don’t actually own the building that you’re working out of. For example, are you going to need a commercial insurance policy when you lease an office space, or is that something that’s covered by the building owner themselves? Let’s take a closer look at what you need to know about commercial insurance requirements when you’re renting an office space. Once you’re ready to find a commercial insurance policy, you can come to us here at Wenatchee Insurance Agency, serving Wenatchee, WA and surrounding areas.
Do You Need a Commercial Insurance Policy If You Lease an Office Space?
It can be easy to assume that you don’t need commercial insurance for a building you don’t own. After all, it’s highly likely that the owner of the building has their own insurance policy to cover any unforeseen disasters that might affect their investment. However, it’s very much like any other renter/landlord situation. The property owner’s insurance is designed only to protect them. If something should happen that results in the theft or damage of any of the furniture or electronics you own, or should a person slip and fall at your business and decide to sue you, the office owner’s insurance is not going to cover your business. Whether you own your office building or rent it, you’re going to need commercial insurance regardless.
Seek Out Your Commercial Insurance With Wenatchee Insurance Agency
Wenatchee Insurance Agency, serving Wenatchee, WA, is here to help you find commercial insurance that meets your unique business needs. Our team will help you find and compare policies so that you can be confident you’re making the right choice. Give us a call now and protect your business.
At Wenatchee Insurance, we lend a hand to business owners with a wide background. Business insurance can be tricky. Some are just starting their journey where some have been running their family business for five generations. We even got involved with lending a hand with assisting Enterprise For Equity to help people better insure their business.
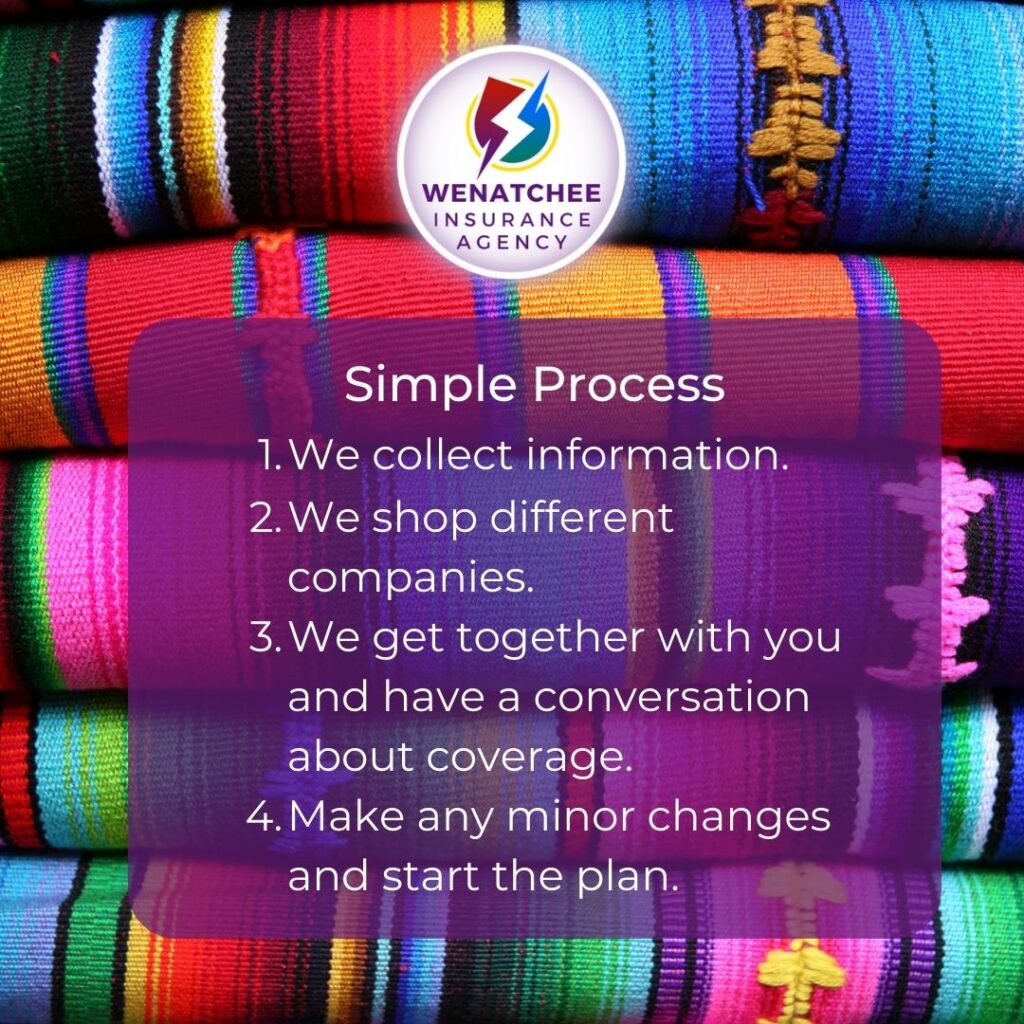
We will ask questions so that we can get a better picture about your business to make sure that you are not creating a coverage gap. For us, we believe that insurance should be:
Affordable. If you can not pay for it then it doesn’t make sense.
Understandable. This creates big problems if someone has something that they don’t know how it works.
Useable. If an emergency arises then we want you to be able to use it.
Retail business insurance questions
1) What is the official name of your business?
2) What is the address where you operate? Is it online only home based?
3) Do you have a different mailing address? If so What?
4) What is a your business phone #?
5) How much do you think you’re going to be making this year?
6) Does anyone else own a stake in the business?
7) Do you use your car to make deliveries?
8) What is the product/s you sell?
9) How many employees will you have?
10) Are there any additional insureds? (Landlords/owners)
11) Anything you think I should know?
What’s next to insure your business?
After collecting the information, we go looking for a good insurance company that fits your business. Some insurance companies may charge more or even not cover something that you need. What works for Farmer Fred in Quincy may completely miss Oliver Orchard in Cashmere. Not everyone needs crop insurance. The old company that your grandfather used may not cover the drones that you are using today.
When you are ready let’s talk. We have found that a conversation is a great way to begin.
Accidents happen. The rain falls, the wind blows, ice forms unexpectedly, or someone simply trips over their own feet. Regardless of the cause, someone was injured on your business premises, and they want you to cover their medical expenses. As a business owner, you have a “duty of care,” meaning you have a responsibility to ensure there is nothing on your property that could harm a potential customer. But as the saying goes, “stuff happens.” Fortunately, this is why you have Commercial Insurance.
What to Do if Someone Is Injured on Your Property
First and foremost, you must attend to the customer’s well-being. Call 911, describe the incident, follow the operator’s instructions, and wait for the paramedics to arrive. Even if you’re unsure, it’s better to call an ambulance. Apply necessary first aid. If the customer refuses an ambulance or the injuries aren’t serious, at least provide them a quiet place to rest and offer ice or a glass of water. Then, you must address the hazard. Block it off if necessary. Document the scene with pictures before you alter anything. Do not admit or imply anyone is to blame. Complete an incident report with the time and date of the accident. Collect statements from witnesses and the injured customer. Save any surveillance footage you may have. Once all of this is covered, you should contact your insurer as soon as possible.
Many types of Commercial Insurance
Commercial Insurance has been more than basic liability for years. Sometimes you need a business owners’ policy that can cover employee theft. Sometimes you need liquor liability, a bond, commercial auto, insuring your equipment on the job site for theft or completed goods. We like to have conversations so that if there is a claim that you understand your coverages better before you need them.
Contact Wenatchee Insurance Agency in Wenatchee, WA
If you are in the Wenatchee, WA area and need commercial insurance, please contact Wenatchee Insurance Agency. We’re here to help.
Why You Should See Shayla at Wenatchee Insurance for a Surety Bond (And Avoid the DIY Disaster)
Let’s talk about bonds. No, not the kind James Bond carries around in his secret spy wallet—though that would be cool. We’re talking about surety bonds, contractor bonds, notary bonds, and all the other fun financial guarantees that businesses and individuals sometimes need. If that sounds about as exciting as watching paint dry, don’t worry—Shayla at Wenatchee Insurance makes the process painless, simple, and, dare we say, almost enjoyable.
Surety Bonds Are Confusing. Shayla Is Not.
If you’ve ever tried to Google “how to get a surety bond in Washington state,” you probably ended up in a confusing rabbit hole of legal jargon, application forms, and requirements that make no sense. That’s because bonds involve three parties—the principal (you), the obligee (the entity requiring the bond), and the surety (the insurance company backing it). Still with us?
Good news: You don’t need to memorize any of this. Shayla already knows it all. She translates “insurance-speak” into plain English so you understand exactly what you need and why. No more guesswork, no more frustration—just straightforward answers.
Speed Matters—And Shayla Delivers
Need a bond fast? Maybe you just landed a big job as a contractor and need a license bond yesterday. Or perhaps you suddenly realized that your business permit requires a specific bond you didn’t even know existed. Instead of panicking, just call Shayla. She works quickly to get you bonded ASAP so you can move forward with your business (and avoid that scary fine from the state).
Plus, trying to go it alone can lead to mistakes. A small paperwork error could mean delays, rejections, or worse—paying too much for a bond that doesn’t even cover what you need. Shayla knows how to navigate the system, ensuring you get the right bond at the best price, with zero headaches.
Sure, you could go online and try to get a bond through some faceless website. But do you really want to deal with a call center in who-knows-where when something goes wrong? With Shayla, you’re working with someone who understands Wenatchee, North Central Washington, and all the specific requirements of our state.
More importantly, she actually cares. Need a reminder when your bond is about to expire? She’s got you covered. Not sure if your business needs additional bonding? She’ll walk you through it. Try getting that level of service from a random internet company.
The Bottom Line: Call Shayla
If you need a bond, don’t make it harder than it has to be. Skip the stress, save time, and go straight to the expert. Call or visit Shayla at Wenatchee Insurance—because when it comes to bonds, it’s always better to have a local expert in your corner.
Need help today? Shayla’s ready—give her a call before you find yourself tangled in a web of bond confusion!
Lowering your commercial auto insurance premiums is like finally reaching that itch you couldn’t scratch. Let’s dive into the tips and tricks that can help you save money while keeping your business progressing forward.
Clean Driving Records: The A plus on your high school report card
Think of your driving record like your report card. The better it is, the happier your insurance company will be. If your employee, Larry, has a habit of speeding down Wenatchee Avenue, it’s time for a chat. Remind him to slow down and drive safely – it’s not a race to Plaza Wenatchee before they run out of Carne Asada!
Telematics Programs: The Tiny Coach in Your Vehicle
These little gadgets track driving habits and reward safe drivers with lower premiums. It’s like having a tiny coach riding along, cheering every time you avoid a sudden stop or a tight turn. Install one in each vehicle, and watch the savings roll in like tumbleweeds on the road to Quincy. Wenatchee Insurance provides telematics programs that are easy to implement and can provide real-time feedback to help your drivers stay safe and your premiums low.
Raise Your Deductibles: The Bigger Tank Approach
Higher deductibles can lower your premiums. Just make sure you have the funds for the deductible if something does happen. It’s like having a bigger gas tank, you fill up a few times a month but when you do, it takes more from your bank account. Wenatchee Insurance can help you find the perfect balance between deductible and premium, ensuring you’re comfortable with your coverage.
Bundle Your Policies: The Combo Meal of Insurance
If you’ve got general liability or property insurance, bundle them with your commercial auto policy. It’s like getting a cheeseburger and curly fry combo – everything together is cheaper than buying each item separately. Insurance companies prefer multi-policy accounts. Independent agencies like Wenatchee Insurance can offer a wide variety of bundling benefits.
Shop Around: The Farmers Market Approach
Wenatchee Insurance can shop around on your behalf, ensuring you get the best deal without the hassle. We compare rates from different insurers like you’re checking out apples at the farmer’s market. Each one might offer different discounts or better rates for the same coverage. As an independent agency, we have options.
Use Vehicles Wisely: Choose the Right Ride
The type of vehicle you use can impact your insurance rates. A shiny red, sports car used for pizza delivery is going to cost more to insure than a modest pickup truck. Evaluate your fleet with Wenatchee Insurance’s help to ensure you’re using the most cost-effective vehicles for your business needs.
Consistent Coverage: Avoid Lapses
Lapses in coverage can lead to higher premiums when you reapply. Keep your insurance active and consistent. Think of it as maintaining coverage like dating, what would you think if the person kept you waiting at the restaurant to show up? Wenatchee Insurance can set up automatic payments and reminders to ensure you never miss a due date, keeping your coverage uninterrupted.
Review and Adjust Annually: Stay Updated
Your business evolves and stays current with the times, and so should your insurance. Review your policies annually with Wenatchee Insurance to make sure you’re getting the best rates and coverage for your current needs. We are not using the same phones from ten years ago, why is your insurance different? These yearly checkups are important.
Reward Safe Drivers: Incentivize Good Behavior
Create a rewards program for your employees who maintain clean driving records. Gift cards, bonuses, or even a monthly “Safe Driver of the Month” parking spot can motivate your team to drive safely.
Consult an Expert: Wenatchee Insurance Is Here for You
Navigating the world of commercial auto insurance can be tricky, but you don’t have to do it alone. Shayla with Wenatchee Insurance can provide personalized advice and solutions tailored to your business. From initial quotes to ongoing support, they’re your partner in keeping insurance costs low and coverage high.
So, next time you’re sipping a coffee from Little Red’s Espresso, think about these tips. Implementing them with the help of Wenatchee Insurance can transform your insurance experience from a daunting task to a smooth ride.
Topics: Progressive, Commercial Auto, company car, collision coverage, collision coverage, delivery, Wenatchee Insurance, Chelan County, Grant County, Douglas County, Okanogan,
Alright, let’s break this down with a story. Meet Sofia. She lives in Waterville and loves two things: her dog, Diego, and her food truck, “Sofia’s Snack Shack Supreme,” which serves the best Burritos north of the Rio Grande. Now, Sofia drives her personal Subaru to pick up Diego’s favorite treats at Firehouse Petshop and her food truck to cater events over in Chelan. She would need both personal and commercial auto insurance, but why?
Personal auto insurance is like your trusty sidekick for everyday life. It covers you when you’re driving to pick up groceries at Safeway or heading to Lincoln Rock State Park for a hike. It’s all about personal use – commuting, road trips, and family outings.
But when Sofia hops into her food truck to cater a wedding at Ohme Gardens, she’s in the realm of commercial auto insurance. This is because commercial auto insurance covers vehicles used for business purposes. Whether you’re transporting goods, driving clients, or in Sofia’s case, serving up those mouth-watering burritos, commercial auto insurance has your back.
One day, Sofia’s food truck gets a dent while navigating the narrow streets of downtown Leavenworth. Because it happened during business hours while she was serving customers, her commercial auto insurance steps in. Her personal auto insurance would’ve thrown its hands up and said, “Not my job, no lettuce for you!”
Another difference? Liability limits. Commercial policies typically have higher liability limits because businesses face greater risks. If Sofia’s food truck accidentally bumps into the famous May Pole in Leavenworth, she’d need more coverage than if she just tapped a neighbor’s mailbox with her little Subaru.
Finally, let’s talk about employees. If Sofia hires a driver for her food truck, commercial auto insurance covers them too. Personal policies? Not so much. They’re like that one friend who never wants to share their fries – they only cover you and not anyone else driving your car for business.
So, next time you see Sofia cruising around in her Burrito truck, remember personal auto insurance is for personal rides, and commercial auto insurance is for business wheels. It’s the difference between a joyride and a job ride!
Topics: Progressive, Commercial Auto, company car, collision coverage, collision coverage, delivery, Wenatchee Insurance, Chelan County, Grant County, Douglas County, Okanogan,
Picture this: You run a small but mighty landscaping business, Green Thumb Gurus, in beautiful sunny Wenatchee. You and your team zip around town, trimming hedges and mowing lawns from Eastmont Community Park to the Cashmere Pioneer Museum. Now, do you need commercial auto insurance for your small business? Simply put, yes!
Here’s why. If you’re using your pickup truck for business purposes, your regular auto insurance might not cover you if you get into an accident while hauling a load of mulch to a client’s yard. That’s right – your insurance could say, “Not my problem!” faster than a teenager ditching household chores. A commercial auto or business endorsement will save you headaches in the future.
We never want to give an insurance company an excuse not to cover a claim. When you are doing business on a personal policy they you are one step closer for them to do just that.
Commercial auto insurance is the brave big brother where personal auto insurance fears to walk. It covers vehicles owned by your business, whether it’s a shiny new pickup truck or that old grey panel van with the dented door you’ve lovingly nicknamed “The Battleship.” If it’s used for business, it needs commercial coverage.
Let’s say you’re driving through Leavenworth after a successful day of planting tulips, and you get rear-ended by a wine tourist bus. Without commercial auto insurance, you’d be on the hook for repairs and medical bills. Ouch!
Not convinced? Picture this: One of your employees, Greg, uses his own car to deliver a bigfoot chainsaw carving (because who doesn’t love bigfoot in Washington state?). If Greg gets into an accident, your business could be held liable. Commercial auto insurance can cover those costs, saving your business from financial ruin.
So, whether you’re delivering flowers, catering weddings, or running errands, if it’s business-related, get commercial auto insurance. It’s a small price to pay for peace of mind, and it’ll keep your business running smoothly, from the woods of Lake Wenatchee to the hills of the Okanogan Highlands.
Topics: Progressive, Commercial Auto, company car, collision coverage, collision coverage, delivery, Wenatchee Insurance, Chelan County, Grant County, Douglas County, Okanogan,
For nearly a decade we have assisted with Health & Medicare Solutions. We are proud to be selected by the Washington Healthplanfinder to be one of ten Enrollment Centers located in Washington State.